Claims
What to Do When Making an Insurance Claim
Knowing the general steps before something goes wrong can make a claim clearer and help you avoid avoidable delays.
By Tasman Insurance Group4 min read
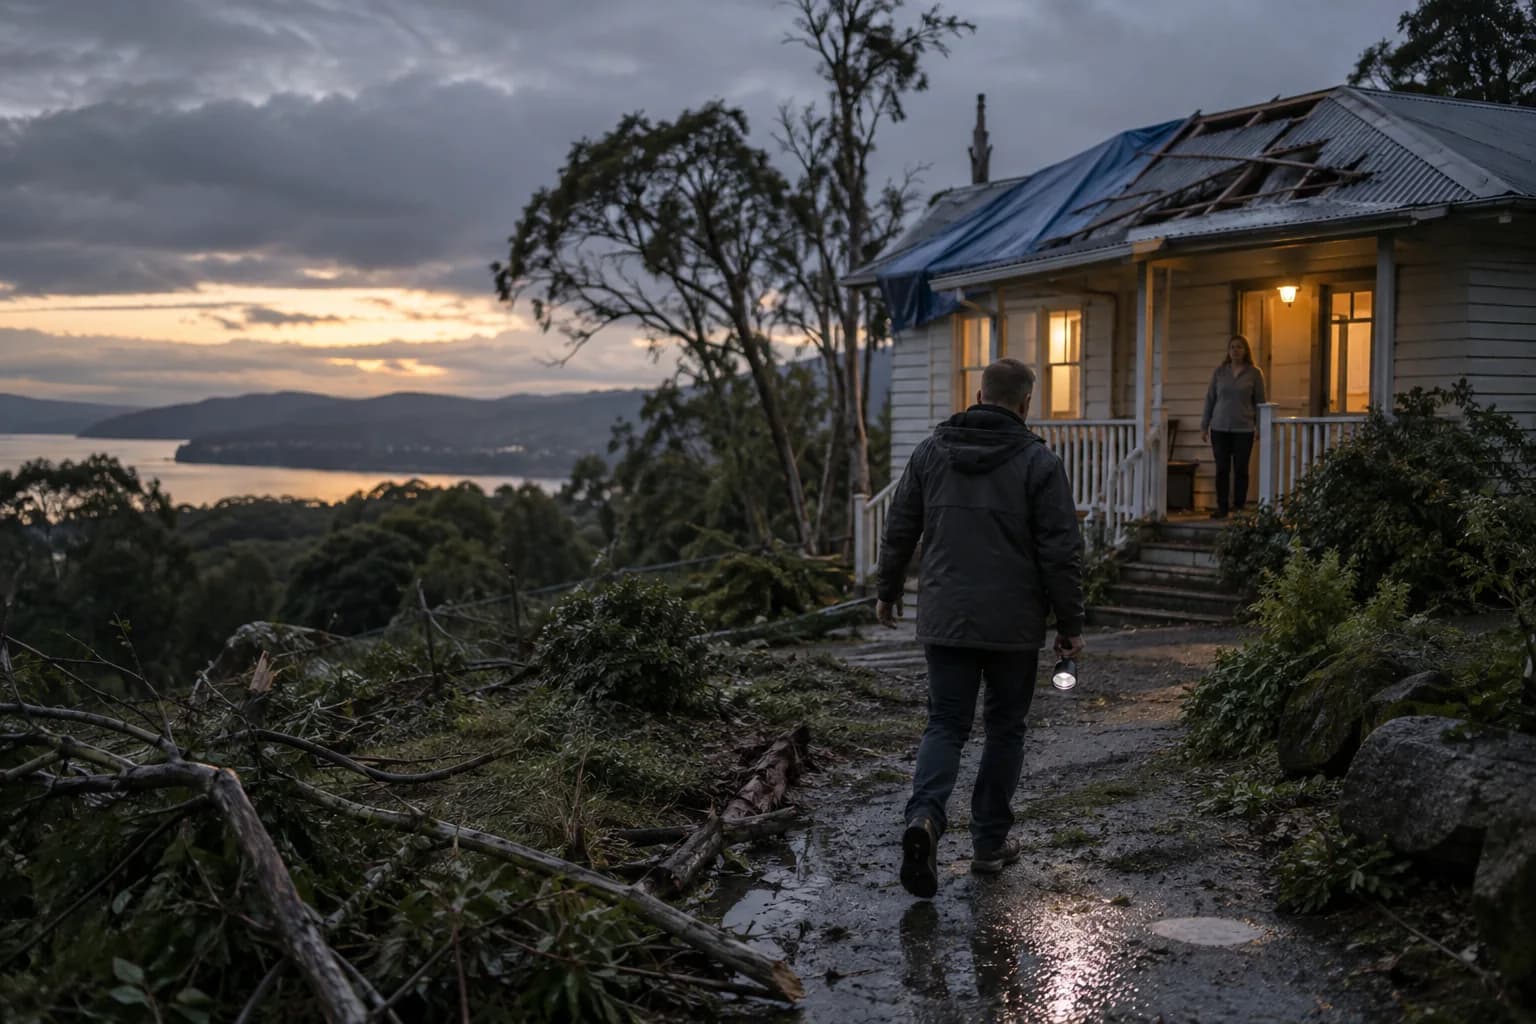
Making a claim usually happens at a stressful time. Knowing the general steps in advance can make the process clearer and help you avoid problems that could delay or affect the outcome.
This guide applies broadly to both business and personal policies, although each policy sets out its own claims conditions. Always check your wording for the specific requirements.
Straight after the event
Make things safe
Your first priority is the safety of people. If there is a risk to life or health, call emergency services. Once it is safe, take reasonable steps to prevent further damage, such as covering a damaged roof or turning off water or power where appropriate.
Most policies expect you to take reasonable steps to minimise further loss. Keep receipts for emergency repairs or temporary measures, as some of these costs may be claimable depending on the policy.
Record what happened
Before anything is cleaned up or thrown away, take photos and video of the damage. Write down what happened and when, while it is fresh in your mind.
- Photos and video of all damaged areas and items
- Dates, times and a short description of events
- Names and contact details of any witnesses
- Police event or report numbers where theft, vandalism or a road accident is involved
- Details of any other party involved, including their insurer if known
Try not to dispose of damaged items until the insurer or its assessor has said it is okay. They may need to inspect them.
Notifying your insurer
Contact your insurer or broker as soon as practicable. Policies usually require prompt notification, and delays can make it harder to assess what happened.
You will generally be asked for your policy number, a description of the event and an estimate of the damage or loss. For liability matters, such as someone alleging you injured them or damaged their property, let your insurer know before you respond in detail to the other party.
Admissions of liability
Many liability policies include a condition that you must not admit fault or agree to pay compensation without the insurer's consent. Being courteous and exchanging details is fine, but avoid promising to cover someone's costs at the scene. Doing so may affect your cover.
What happens during assessment
For larger or more complex claims, the insurer may appoint a loss adjuster or assessor. Their role is to investigate the circumstances, inspect the damage and report on the claim. They may ask for documents such as invoices, financial records, maintenance logs or repair quotes.
Responding to reasonable requests promptly can help keep the claim moving. If something is unclear, ask what is needed and why.
Keep copies of everything you send and receive, and make a note of phone conversations, including the date and who you spoke with. A simple folder, paper or digital, makes it much easier to follow up if questions come up later in the process.
- Lodge the claim and receive a claim number
- Provide the information and documents requested
- Allow an inspection or assessment if required
- Receive the insurer's decision on whether the claim is accepted, in whole or in part
- Arrange repair, replacement or settlement, subject to any excess and the policy terms
Your excess will usually be deducted from the settlement or payable separately. The amount and how it applies are set out in your schedule and policy wording.
If you are unhappy with the outcome
If a claim is declined, or you disagree with how it has been handled, start by asking the insurer for its reasons in writing. Each insurer has an internal dispute resolution process, and you can lodge a complaint through it.
If the matter is not resolved, you may be able to take it to the Australian Financial Complaints Authority (AFCA), an independent external dispute resolution body. Eligibility depends on the type of policy and the circumstances, so check the insurer's complaints information for details.
Where you have a broker, they can help you prepare the claim, follow up with the insurer and explain the decision. If your policy was arranged through Tasman Insurance Group, contact us early and we can talk you through the next steps.
This article is general information only and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, read the relevant Product Disclosure Statement and policy wording, and speak with a licensed adviser about your circumstances.