Public & Product Liability Insurance
Public liability insurance relates to claims from third parties who are injured, or whose property is damaged, because of your business activities. Product liability extends this to goods you make, sell, supply or import.
The two are commonly arranged together in one policy. Legal defence costs may also be included, depending on the wording.
Who this insurance may suit
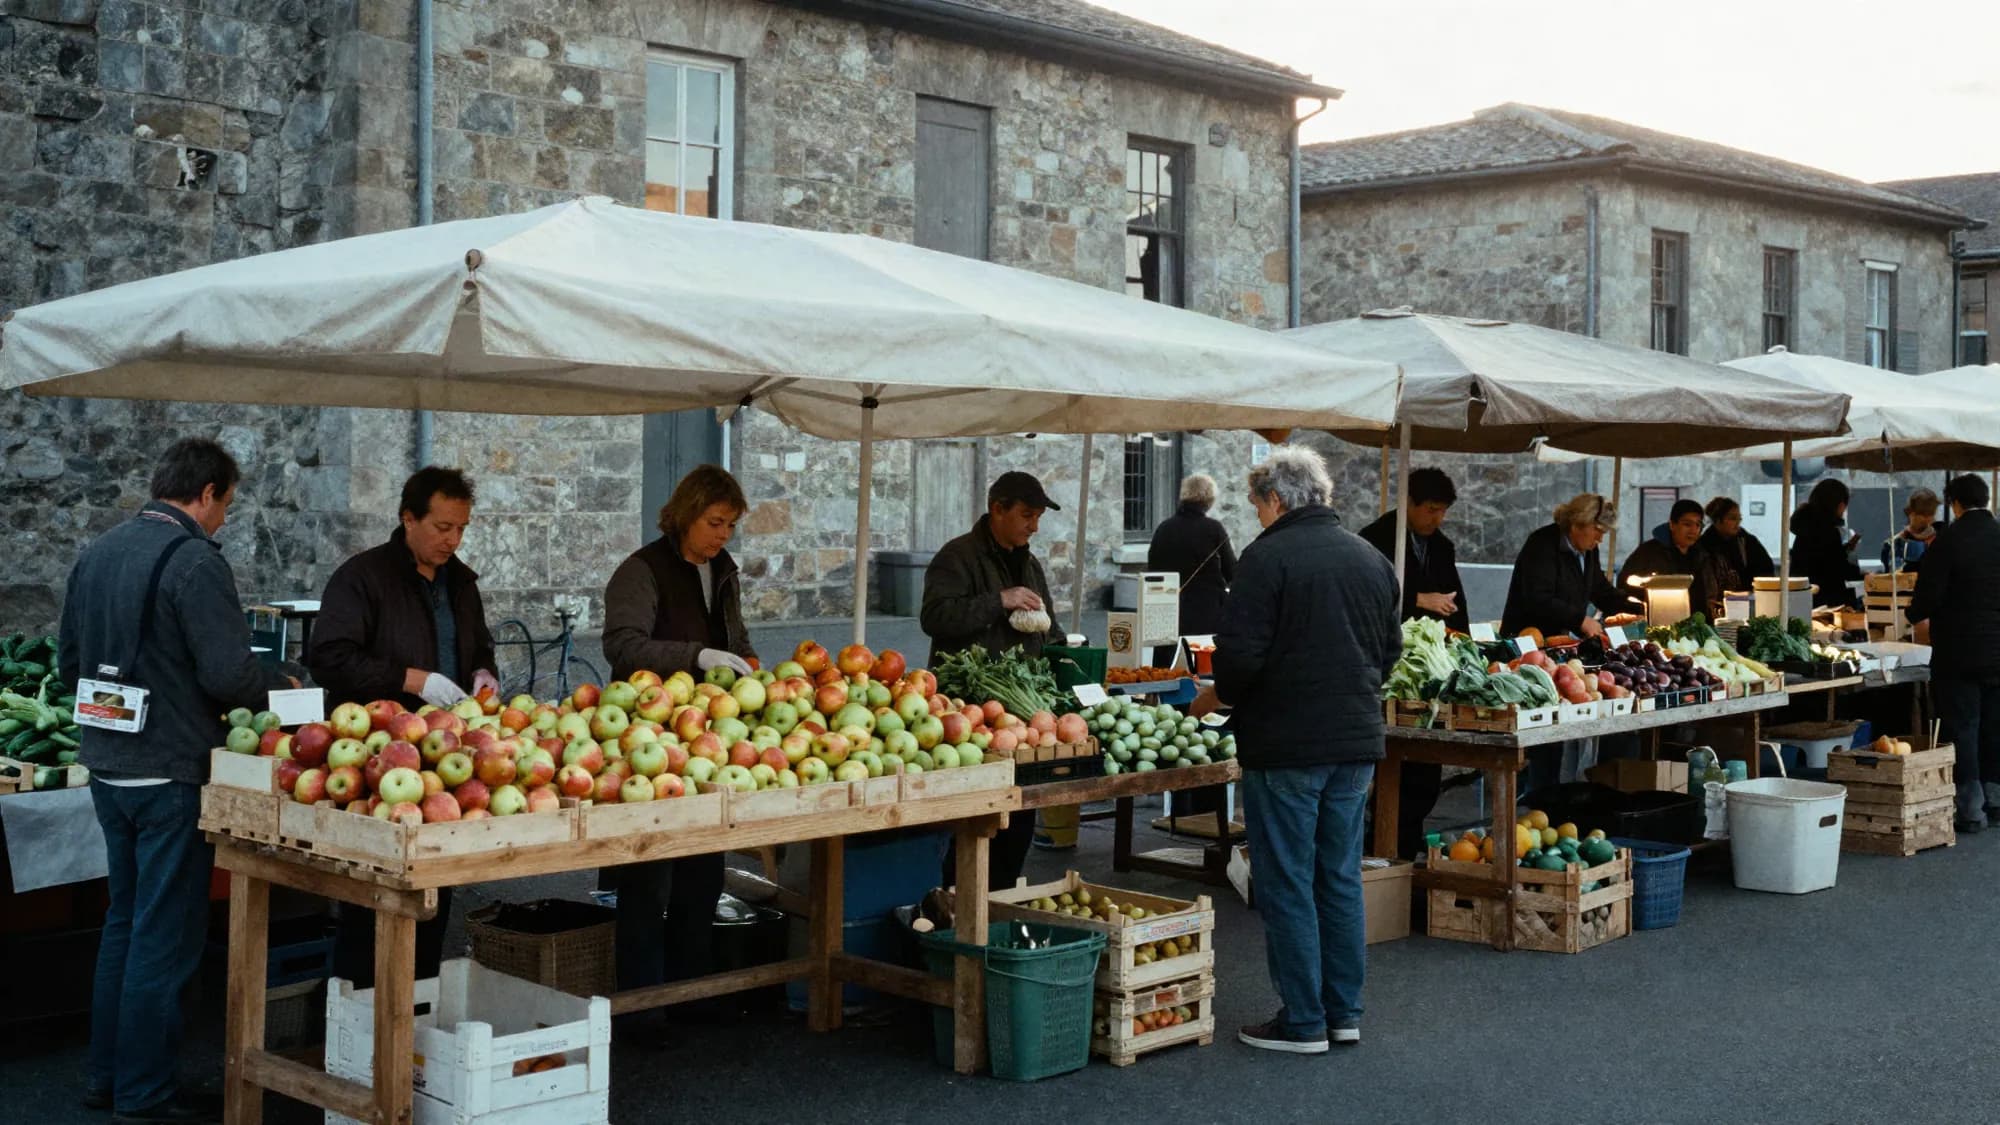
- Market stallholders and event vendors
- Retailers and hospitality businesses
- Tradies and contractors working at client sites
- Manufacturers, importers and wholesalers
- Fitness instructors, coaches and personal service providers
- Businesses that host visitors on their premises
Why this cover may be important
Claims for injury can involve medical costs, lost earnings and legal fees. Even a claim that is defended successfully may carry significant costs.
Councils, venues, market organisers and head contractors often require evidence of public liability before you can trade or start work.
Potential areas of cover
Cover varies between insurers and policies. Depending on the policy, cover may include:
Injury to third parties
The policy may respond to claims from customers, visitors or members of the public injured in connection with your business.
Damage to third party property
Cover may include accidental damage you cause to property owned by others, such as a client's floor or fittings.
Product liability
If a product you supply causes injury or property damage, product liability may respond, subject to the policy's terms.
Legal defence costs
Many policies cover reasonable costs of defending a claim, which can apply whether or not the claim succeeds.
Limit of indemnity
You choose a limit that sets the maximum the insurer will pay. Contracts often specify a minimum limit.
Common risks
- A customer slipping on a wet floor
- Damage to a client's property while working on site
- A faulty product causing injury
- Food products causing illness
- A visitor tripping over equipment or stock
- Claims arising at markets, events or pop-up stalls
What may not be covered
Every policy has exclusions, limits and conditions. Some common considerations include:
- Injury to your own employees is generally handled by workers compensation, not public liability.
- Damage to property in your care, custody or control may be limited or excluded.
- Professional advice and design errors usually fall under professional indemnity instead.
- Products exported to some overseas markets may require specific disclosure or cover.
- Contractual liability you accept beyond the law may not be covered.
Always read the Product Disclosure Statement and policy wording. Your broker can explain how they apply to you.
Why work with Tasman Insurance Group
- We take time to understand your business or circumstances before discussing cover.
- Where applicable, we approach suitable insurers and compare the options available.
- We explain exclusions, limits and excesses in plain English before you decide.
- We help with changes during the year, renewals and claims.
Public & Product Liability Insurance FAQs
What is the difference between public and product liability?
Public liability relates to your business activities, such as work at a site or visitors at your shop. Product liability relates to goods you supply. They are often combined in one policy.
How much public liability cover do I need?
Many contracts and venues set a minimum limit. Beyond that, the right limit depends on your activities and exposure. A broker can talk through your situation.
Does public liability cover my employees if they are injured?
Generally no. Employee injuries are handled through workers compensation, which is compulsory for employers and arranged through state schemes or authorised insurers.
I only sell at weekend markets. Do I still need cover?
Many market organisers require stallholders to hold public and product liability. Short-term or annual options may be available depending on the insurer.
Related insurance solutions
Business Insurance
A package policy that can bring several types of business cover together, arranged around how your business actually runs.
Learn more about Business InsuranceProfessional Indemnity Insurance
Cover that may respond to claims alleging an error, omission or negligence in the advice or services you provide.
Learn more about Professional Indemnity InsuranceTrades Insurance
Cover options for tradies, bringing together liability, tools, vehicles and income protection around your trade.
Learn more about Trades Insurance
Ready to talk about public & product liability?
Request a quote or call us. We'll ask about your circumstances and discuss the options available.